Sales tax in restaurants looks simple on the surface. In practice, however, it's one of the most common ways owners find themselves facing an audit, a penalty, or worse.
Running a restaurant means juggling payroll, food costs, staffing, and a dining room full of people who just want their order fast. Taxes rarely make that list of daily worries. But indirect tax compliance deserves a spot near the top, because restaurants are consistently among the most audited businesses in any state.
What Makes A Tax ‘Indirect’
A direct tax, like corporate income tax, is paid straight to the government. An indirect tax works differently. The restaurant collects it from the customer at the point of sale, then passes it along to the state. Sales tax is the clearest example, and in many states, so are excise taxes on alcohol.
That collection role comes with real weight. Because the money technically belongs to the state the moment it's collected, it's treated as a "trust fund tax." The business and its responsible individuals can be held personally liable for the full unpaid amount, plus interest, if it isn't remitted. The Internal Revenue Service (IRS) applies this same trust fund concept to federal payroll withholding, and courts have consistently upheld personal liability for whoever controls the money, regardless of whether the business operates as a corporation or an LLC.
Why Sales Tax In Restaurants Gets Complicated Fast
The obvious part is charging sales tax on a bill. The harder part is knowing when not to.
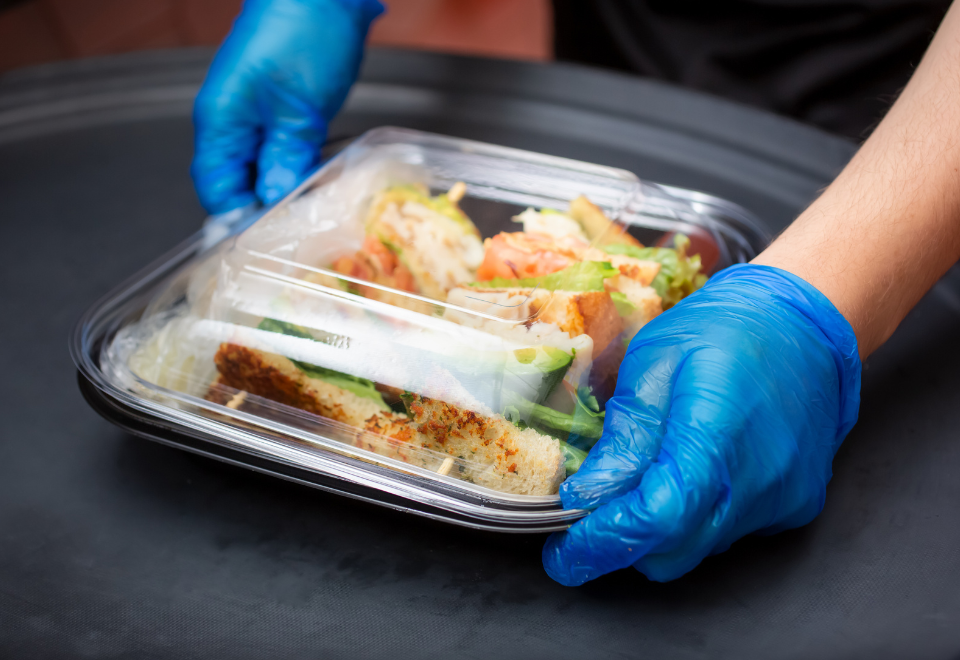
Ohio is a good illustration. The Ohio Department of Taxation taxes food based on where it's eaten, not what it is. A sandwich eaten in the dining room is taxable. The same sandwich boxed up for takeout is exempt. Soft drinks break the pattern entirely: they're taxable every time; dine-in or to-go, while plain coffee, tea, and milk stay exempt unless sweetened. Alcohol adds another layer, since beer, wine, and liquor sales can carry separate excise tax obligations on top of standard sales tax.
Ohio is just one example of how widely restaurant sales tax rules can differ across the country. Every state—and, in some cases, local jurisdiction—has its own definitions, exemptions, tax rates, and treatment of dine-in meals, takeout orders, beverages, alcohol, delivery fees, and other charges. A practice that is correct in one state may produce an underpayment or overcollection of tax in another.
Multiply those distinctions across a menu with dozens of items, a few delivery platforms, multiple locations, and a staff trained to move fast, and it’s easy to see how errors creep in without anyone intending to break a rule.
Good Records Are The Best Defense
When an audit happens, and for restaurants, the odds are higher than for most other industries, the strength of your books determines the outcome. Auditors look for a clear paper trail: dine-in versus takeout sales; alcohol sales tracked separately from food; gratuities and delivery fees handled consistently; and documentation for any exempt sale. Gaps in that trail don't just slow down an audit. They can push an examiner toward broader estimation methods that assume more tax is owed than your actual sales would show.
What Happens When Compliance Slips
The consequences scale with the size of the miss. Interest and penalties come first, then license revocation in serious cases, and personal liability for owners and managers if the shortfall involves collected-but-unremitted tax. States generally offer a way to get ahead of it: voluntary disclosure programs that let a business come forward before an audit starts, pay the tax owed, and in exchange, have penalties waived and the lookback period limited.
That kind of proactive move only works if you catch the issue yourself, which is exactly why so many owners bring in help before a state does.
Talk To A CPA Firm That Knows Restaurants
Indirect tax rules shift often, and restaurants rarely have the bandwidth to track every change while running service. GBQ Partners specializes in working with restaurant owners and operators nationwide on sales tax questions, audit preparation, and broader accounting needs specific to the hospitality industry. If you're unsure whether your current setup will hold up in an audit, contact GBQ to talk through your options. Our State & Local Tax team is ready to answer your questions and find solutions tailored to your unique needs.
Frequently Asked Questions
What is a trust fund tax?
It's tax money a business collects from customers, such as sales tax, and holds temporarily before remitting it to the state. Because the funds aren't the business's own money, mishandling them can create personal liability for owners and managers.
Can a restaurant owner be personally liable for unpaid sales tax?
Yes. Operating as a corporation or LLC doesn't shield an owner from liability for unremitted trust fund taxes in most states.
Is takeout food taxed the same as food eaten in the restaurant?
Not usually. Many states, including Ohio, exempt food sold for off-premises consumption while taxing the same item when eaten on-site. Soft drinks are a common exception and stay taxable either way.